Quick Answer
Covered trades default to T+1 unless expressly agreed otherwise at trade time. Excluded securities follow separate rules or conventions. Specified registered firm-commitment offering sales priced after 4:30 p.m. ET default to T+2. Covered allocation, confirmation, and affirmation workflows must finish as soon as technologically practicable, by trade-date end, supported by agreements or reasonable written procedures.
The T+1 settlement cycle is the regulatory backbone of post-trade operations. The principal must understand the standard cycle, the exemptions that escape it, and the same-day affirmation requirement that supports it.
The Standard T+1 Cycle
The SEC's settlement-cycle rule is short and direct:
A broker-dealer generally may not contract for settlement later than T+1 in a covered transaction unless the parties expressly agree to a different date at the time of the transaction. The rule also specifies excluded transactions.
The cycle was shortened from the prior T+2 standard to T+1, effective May 28, 2024.
The shorter cycle was driven by:
- Risk reduction (less time for counterparty risk to materialize between trade and settlement)
- Capital efficiency (NSCC margin requirements scale with the settlement window)
- Operational modernization (post-2020 GameStop/meme-stock episode prompted faster settlement)
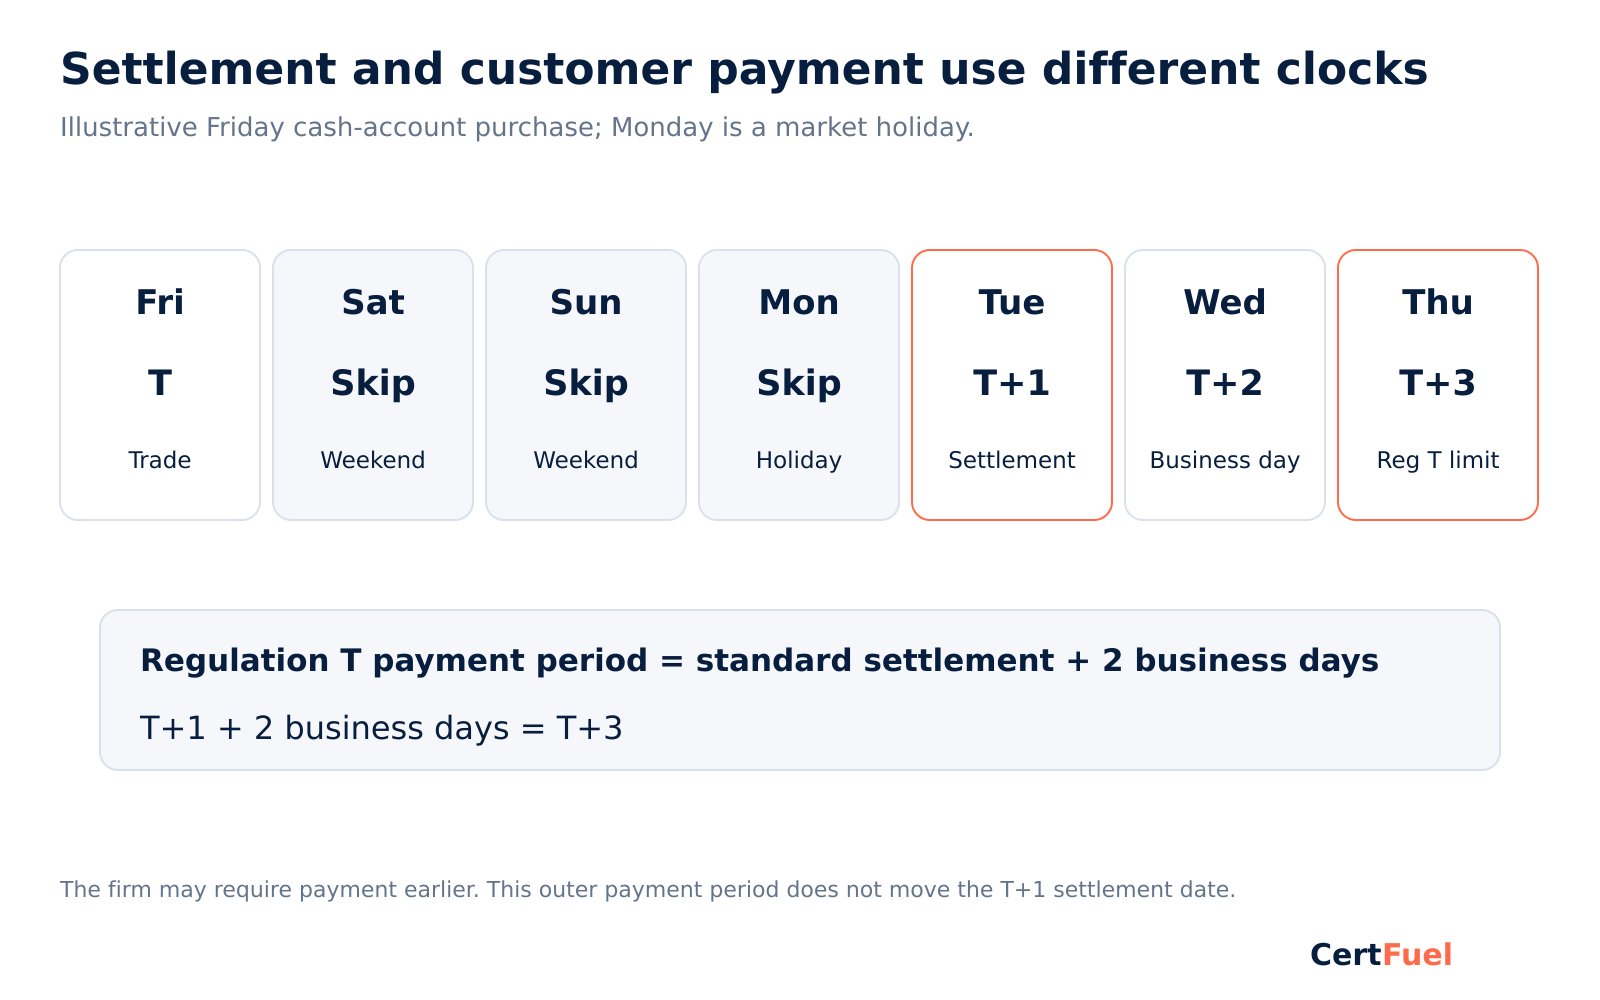
Settlement is not the Regulation T payment date. A cash-account customer has until S+2, two business days after settlement, or T+3 for a regular-way T+1 trade, to pay.
Exemptions from the Standard Cycle
Several categories are exempt from the T+1 requirement and trade on their own conventional cycles:
| Exempt Category | Why Exempt |
|---|---|
| Exempted securities | Statutory exemption from securities-act treatment |
| Government securities (U.S. Treasuries) | Trade on their own next-day convention |
| Municipal securities | Governed by MSRB; conventionally T+1 by industry practice |
| Commercial paper | Short-term debt; conventionally same-day or next-day |
| Bankers' acceptances | Short-term debt; conventional cycles |
| Commercial bills | Short-term debt; conventional cycles |
Firm-Commitment Offering Carve-Out
The special T+2 default covers specified sales for cash in a registered firm-commitment offering priced after 4:30 p.m. ET: sales by the issuer to an underwriter or by a participating broker-dealer to an initial purchaser. The parties may expressly agree otherwise at the time of the transaction. Other provisions permit issuer/managing-underwriter settlement agreements for offering sales.
The reason: the SEC added this carve-out in 1995, when commenters said a final prospectus was difficult to print and deliver by settlement for securities priced late in the day. When the SEC moved the standard cycle to T+1 in 2023, it kept the carve-out at T+2 instead of deleting it.
One business day is not long enough to finish an offering's documentation and to fix problems that appear only after pricing, such as transfer-agent, legend-removal or medallion-guarantee issues. The parties can agree to a longer cycle only at the time of the transaction, so without the T+2 default a late problem would cause a failed settlement.
Exam Tip: Gotchas
- T+1 is the standard; excluded securities follow separate rules or conventions.
- The late-priced registered firm-commitment T+2 default applies to the two specified cash sales, not every offering trade.
- Distinguish T+1 settlement from the Regulation T payment date.
Same-Day Allocation, Confirmation, and Affirmation
When a broker-dealer engages with other parties in an allocation, confirmation, or affirmation process for a transaction covered by the SEC's general settlement-cycle requirement, it must either:
- Have a written agreement to complete allocation, confirmation, and affirmation as soon as technologically practicable and by end of the trade date, OR
- Maintain written policies and procedures reasonably designed to ensure same-day affirmation
The rule supports timely settlement by requiring a covered workflow to finish as soon as technologically practicable and no later than trade-date end. Delays increase settlement risk; they do not make next-day settlement physically impossible in every case.
Why Same-Day Affirmation Matters
The post-trade flow for an institutional trade is:
| Step | What Happens |
|---|---|
| Allocation | Asset manager tells broker-dealer how to allocate the block trade across subaccounts |
| Confirmation | Broker-dealer sends a confirmation to the custodian (DVP/RVP) reflecting the allocation |
| Affirmation | Custodian agrees ("affirms") the trade details and settles via DTC on T+1 |
If any of those steps slips past trade date, the trade can go into settlement with mismatched bookings. The result can be fails, breaks, and potentially mark-to-market exposure on uncompleted contracts.
The principal must verify that the firm has the required agreements or written policies and procedures for covered workflows. Scope follows the transaction and the broker-dealer's participation, not an account label. Asset class matters only through the exclusions: a Treasury, municipal, or commercial paper trade is not a covered transaction, so its workflow is outside the requirement.
Exam Tip: Gotchas
- Covered allocation, confirmation and affirmation must finish as soon as technologically practicable and no later than trade-date end.
- The firm needs either a written agreement or reasonably designed written policies and procedures.
Dates of Delivery
The Uniform Practice Code's dates-of-delivery rule defines five trade types, each with its own delivery convention. Cash, regular way and seller's option are the three you meet most often:
| Trade Type | Delivery Timing |
|---|---|
| "Cash" | At the office of the purchaser on the day of the transaction |
| "Regular way" | At the office of the purchaser no earlier than T+1 (current standard) |
| "Seller's option" | On the date the option expires; seller may deliver earlier on any business day after the first business day post-trade with prior written notice |
| "Buyer's option" | On the date the option expires |
| "Delayed delivery" | On the date the parties agreed at the time of the trade |
The "regular way" type is the default and the most common. "Cash" and "seller's option" are alternative arrangements that the parties must specifically agree to.
Seller's Option Mechanics
The name is misleading if you come from a listed-options background. A "seller's option" trade is not a call or a put, and no premium changes hands. It is a settlement convention: the two parties to a regular securities trade agree that the seller gets to pick the delivery date, within a window, instead of delivering on the standard T+1 date.
A "seller's option" trade gives the seller flexibility on the delivery date:
- The parties agree to a delivery date that is later than regular way
- The seller may deliver on the option expiration date
- The seller may also deliver earlier on any business day after T+1 with prior written notice to the buyer
This arrangement is rare in modern markets but appears on exams as a fact-pattern element.
Delivery with Draft Attached
A separate Uniform Practice Code provision allows a seller to deliver securities along with a draft (sight draft) through a bank, requiring payment before the certificates are released.
This is a delivery-versus-payment intermediary mechanism: the bank holds the certificates and the buyer's payment, releasing the certificates only when payment is made. It exists for cases where the seller does not extend credit to the buyer.
The Uniform Practice Code covers over-the-counter secondary-market trades between members, so the method applies to a member-to-member trade. The test is whether the seller wants payment before the buyer gets the certificates.
The provision sets no condition based on the distance between the parties or on whether the seller has a clearing-agency relationship. Those facts only explain why a firm might ship certificates instead of settling through a clearing agency.
In modern markets, this is largely obsolete because Depository Trust Company (DTC)-based DVP settlement handles the same function more efficiently. But the rule still exists and may appear on the exam.
Exam Tip: Gotchas
- Cash, regular way and seller’s option are delivery conventions; apply their distinct timing.
- Same-day affirmation reduces settlement risk; a delay does not make next-day settlement impossible in every case.
What Should You Check on Exam Day?
- Can you state the standard settlement cycle for a regular way trade, and name three categories exempt from it?
- Can you name the two cash sales in a registered firm-commitment offering that default to T+2 when priced after 4:30 p.m. ET?
- Can you distinguish the trade types, especially cash, regular way, and seller's option, by their delivery timing?
- Do you know what same-day affirmation requires, and why it lowers the risk of fails under T+1 settlement?